Skip to content
PAUL DUNNNMLS #174659 | LENDING TEAM

Paul Dunn's Cash Flow Mortgage Method℠

Put Your Money to Work. Pay Less Mortgage Interest.

What if your paycheck could start reducing your mortgage interest the moment you get paid? With the right mortgage structure, your income and savings can lower the balance used to calculate your daily mortgage interest—while you still have access to available funds when you need them, subject to your loan’s terms.

This is the approach I used when evaluating the mortgage for my own home.

Availability, rates, fees and terms vary by lender and borrower. These products can feature variable interest rates and revolving credit terms.

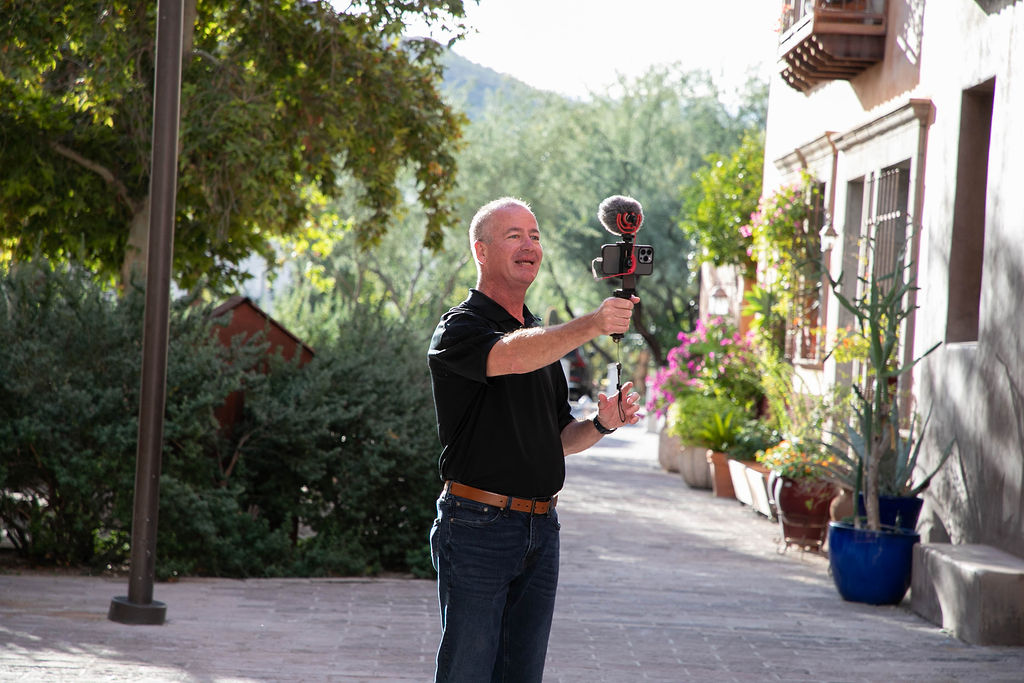
Paul Dunn outdoors holding a camera rig on a walkway

Paul Dunn, Tucson area

Your Money Doesn't Have to Sit on the Sidelines.

With a traditional mortgage and a separate checking account, the money you keep for everyday life generally sits apart from your loan. It doesn't lower the balance your mortgage interest is calculated on.

The Cash Flow Mortgage Method looks at mortgages that work differently. With a linked checking account and a first-lien home equity line of credit, deposits are automatically swept against the loan balance each night. That reduces the balance used to calculate daily mortgage interest for as long as those funds remain applied.

As you pay bills and spend, the balance moves back up. The idea is simple: let money that would otherwise sit idle do some work in between.

— The 30-Year Fixed vs. A Different Approach

Why Does So Much of Your Mortgage Payment Go Toward Interest in the Beginning?

On a standard 30-year fixed mortgage, the principal-and-interest payment generally stays the same. But because you owe the most at the beginning, the interest portion starts out much larger. As your loan balance falls, more of each payment goes to principal.

Traditional 30-Year Fixed Mortgage

  • Steady monthly principal-and-interest payment
  • Early payments are interest-heavy because the balance is highest
  • Depositing your paycheck into a regular checking account doesn't automatically reduce the balance of a traditional 30-year fixed mortgage
  • Fixed rate offers stability; extra principal payments can also lower interest, but accessing home equity may require new borrowing

Hypothetical first payment

$400,000 loan · assumed 6.00% fixed rate · 360 monthly payments

Payment (P&I)
$2,398.20
Interest
$2,000.00
Principal
$398.20

Bar to scale: about 83% interest, 17% principal.

Hypothetical math example only, not a current rate quote or specific lender offer; excludes taxes and insurance. Monthly interest allocation varies with terms and balance.

The Cash Flow Mortgage Method

Paul's approach to analyzing mortgages that pair a first-lien home equity line of credit with a linked checking account.

  • Income and savings deposited to the linked checking account reduce the outstanding balance used to calculate daily mortgage interest
  • Available funds may be withdrawn for bills under the credit-line terms
  • Withdrawals increase the balance again; variable rates, fees, eligibility, terms and actual cash-flow behavior can make it less suitable than a 30-year fixed

Schematic balance movement

Illustrative cash-flow balance movementA schematic line trending downward over time: it drops sharply each time a deposit arrives and rises modestly as bills and withdrawals are paid, across four cycles. No actual values.Time →Outstanding balance
Deposits ↓ balance Spending ↑ balance

Illustrative cash-flow balance movement — not a loan quote, actual savings or a payoff projection.

What if the money moving through your checking account could help lower the balance used to calculate mortgage interest?

That's the possibility we evaluate with The Cash Flow Mortgage Method — not a promise that any one mortgage always wins.

Availability, rates, fees and terms vary by lender and borrower. These products can feature variable interest rates and revolving credit terms.

— How It Works

How Your Cash Flow Goes to Work

  1. Income Arrives

    Your paycheck and other deposits land in the checking account linked to your mortgage.

  2. Deposits Reduce Loan Balance

    Deposits to the linked checking account are swept against the first-lien HELOC balance, reducing the amount on which daily interest is calculated.

  3. Daily Interest Uses the Lower Outstanding Balance

    Interest is calculated on what's outstanding each day—for as long as the funds remain applied.

  4. Use Available Funds as Needed

    Pay bills and spend as permitted by the line terms. Withdrawals raise the loan balance again.

↻ The cycle repeats as income comes in and spending goes out. Interest benefits only last while deposited funds remain applied to the balance.

— Illustrative Example

Illustrative Balance Comparison

Choose an example deposit

Outstanding balance

$400,000

Deposited funds

− $25,000

Balance after deposit

$375,000

Interest now accrues on the lower outstanding balance while funds remain applied.

Illustrative balance movement only, NOT a personalized savings quote, actual payoff estimate, actual rate or loan approval. Real balances change as funds are withdrawn, new charges and interest are added.

Third-Party Simulator

Explore the Numbers for Yourself

The four steps and example above illustrate the mechanics. CMG's comparison simulator lets you explore cash-flow scenarios against a traditional amortizing loan.

All In One Loan Interactive Comparison Simulator — Provided by CMG

This third-party CMG simulator illustrates the daily-balance mechanics of a linked-checking mortgage structure. It is not a quote for a mortgage offered by Paul Dunn Lending Team, and it does not determine whether The Cash Flow Mortgage Method is suitable for you. Actual products, rates and terms vary.

Third-party CMG simulator: content entered in the widget may be processed by CMG under its privacy terms. Nothing loads from CMG until you choose to launch it.

All In One Loan™ is a trademark of CMG Home Loans. The simulator is operated by CMG, not Paul Dunn Lending Team or NEXA Lending; information you enter in it is handled under CMG's terms and privacy practices. Learn more at allinoneloan.com (opens in a new tab).

Paul Dunn outdoors holding a camera rig on a walkway

Paul Dunn, Tucson area

— A Personal Choice

Why I Chose This Approach for My Own Home

When I refinanced my own home, I chose a mortgage structure that lets my income and cash reserves help reduce the balance used to calculate daily interest, while keeping access to available funds under the loan's terms. That's the thinking behind The Cash Flow Mortgage Method. I use this approach in my own finances, so I can explain not only how it works, but also the tradeoffs from firsthand experience.

Talk It Through With Paul (opens Calendly in a new tab)

Is This the Right Fit for You?

It isn't for everyone. It's worth evaluating only after comparing it with other mortgage options.

It may work well when you have...

  • Good credit and substantial available home equity, subject to lender guidelines
  • Strong cash reserves and financial cushion
  • Positive cash flow over time—even when income arrives unevenly
  • Commission-based, seasonal or self-employed income with reserves to cover lean months
  • Comfortable with variable rates, credit-line rules and managing spending

It may be a poor fit when you have...

  • Little or no emergency savings or cash reserves
  • Living paycheck to paycheck without a financial cushion
  • Spending persistently exceeds income over time
  • Limited equity or credit profile outside lender eligibility
  • Need for fixed rates and predictable traditional principal-and-interest payments

Uneven income doesn't automatically mean poor fit. For a commission-based earner, large deposits in stronger months can lower the balance. In leaner months, some credit-line terms may add scheduled interest to the balance while the line has availability—interest still accrues every day. Payment methods and minimum requirements depend on the actual loan. The key is strong reserves, equity, credit, and positive cash flow over time.

Common Questions

Is this a special mortgage that Paul Dunn invented?

No. The Cash Flow Mortgage Method is the name of my educational analysis approach. It's my analysis process for evaluating whether a linked-checking mortgage structure makes sense alongside traditional options. The underlying mortgage structures are offered by external lenders under their own terms, rates and eligibility rules—I didn't create them.

Is this the same as making extra payments?

Not quite. An extra payment on a traditional mortgage is one-way—once it's paid, that money generally isn't accessible without new financing. With a linked-checking first-lien HELOC, deposits reduce the balance, and available funds can be accessed again as permitted by the line terms.

Does the interest reduction happen every day?

These products generally calculate interest on the daily outstanding balance, so a lower balance on a given day means interest accrues on a smaller amount that day. Exact mechanics—like when deposits are applied—vary by product and lender.

Do I still have access to my money?

You can typically access available funds subject to the line's terms and limits. Keep in mind that any withdrawal increases the outstanding balance, and the interest calculated on it.

Are there risks or downsides?

Yes. These loans can have variable rates that change over time, plus fees and specific credit line terms. Results depend heavily on your income and spending habits, and lender eligibility applies. In some situations, the total cost can be higher than a traditional mortgage.

Can I use this when buying or refinancing?

Depending on the lender and your qualifications, both purchase and refinance options can be possible. We'd confirm what's available for your specific scenario.

Will it definitely save more than my current mortgage?

No individual result is guaranteed. The only way to know is to compare actual loan terms against how your money really moves—that's exactly what we'd review together.

Let's See What the Numbers Say for Your Situation.

I'll help you compare this structure with traditional financing using your financial goals, available cash flow, and the actual terms of the loan—so you can decide whether it makes sense.

Ready to Apply? Start Secure Application ↗ (opens Bevri in a new tab)

The Cash Flow Mortgage Method is Paul Dunn's educational analysis approach, not a lender's proprietary loan product or a NEXA Lending program. It is a method for comparing mortgage structures offered by external lenders under their own terms; rates on these structures are typically variable, and no interest savings or payoff timeline is guaranteed. Availability, rates, fees and terms vary by lender and borrower. These products can feature variable interest rates and revolving credit terms.